Private-market investments can be funded from a taxable account or, with more work, from retirement money. What each path involves: taxes, paperwork, and the rules that decide whether it's possible at all.
Before you invest in a private company, you choose which pocket of money funds it. That choice determines your taxes and your reporting, and sometimes whether the investment can happen at all. Most individual investors fund private-market investments from an ordinary taxable account, because it is the simplest path. Retirement money can participate too, usually through a self-directed IRA, but it requires a specialized custodian, follows different tax rules, and runs into a limit inside the deal itself.
Who this is for: investors deciding how to fund a private-market investment for the first time. Most pre-IPO vehicles in the U.S. are limited to accredited investors, as defined under Rule 501 of Regulation D. Using retirement money does not change that: eligibility for an IRA's investment generally looks to the account owner. This module covers account types at a high level; it is not tax advice, and the tax treatment of any specific situation belongs with a qualified tax professional.
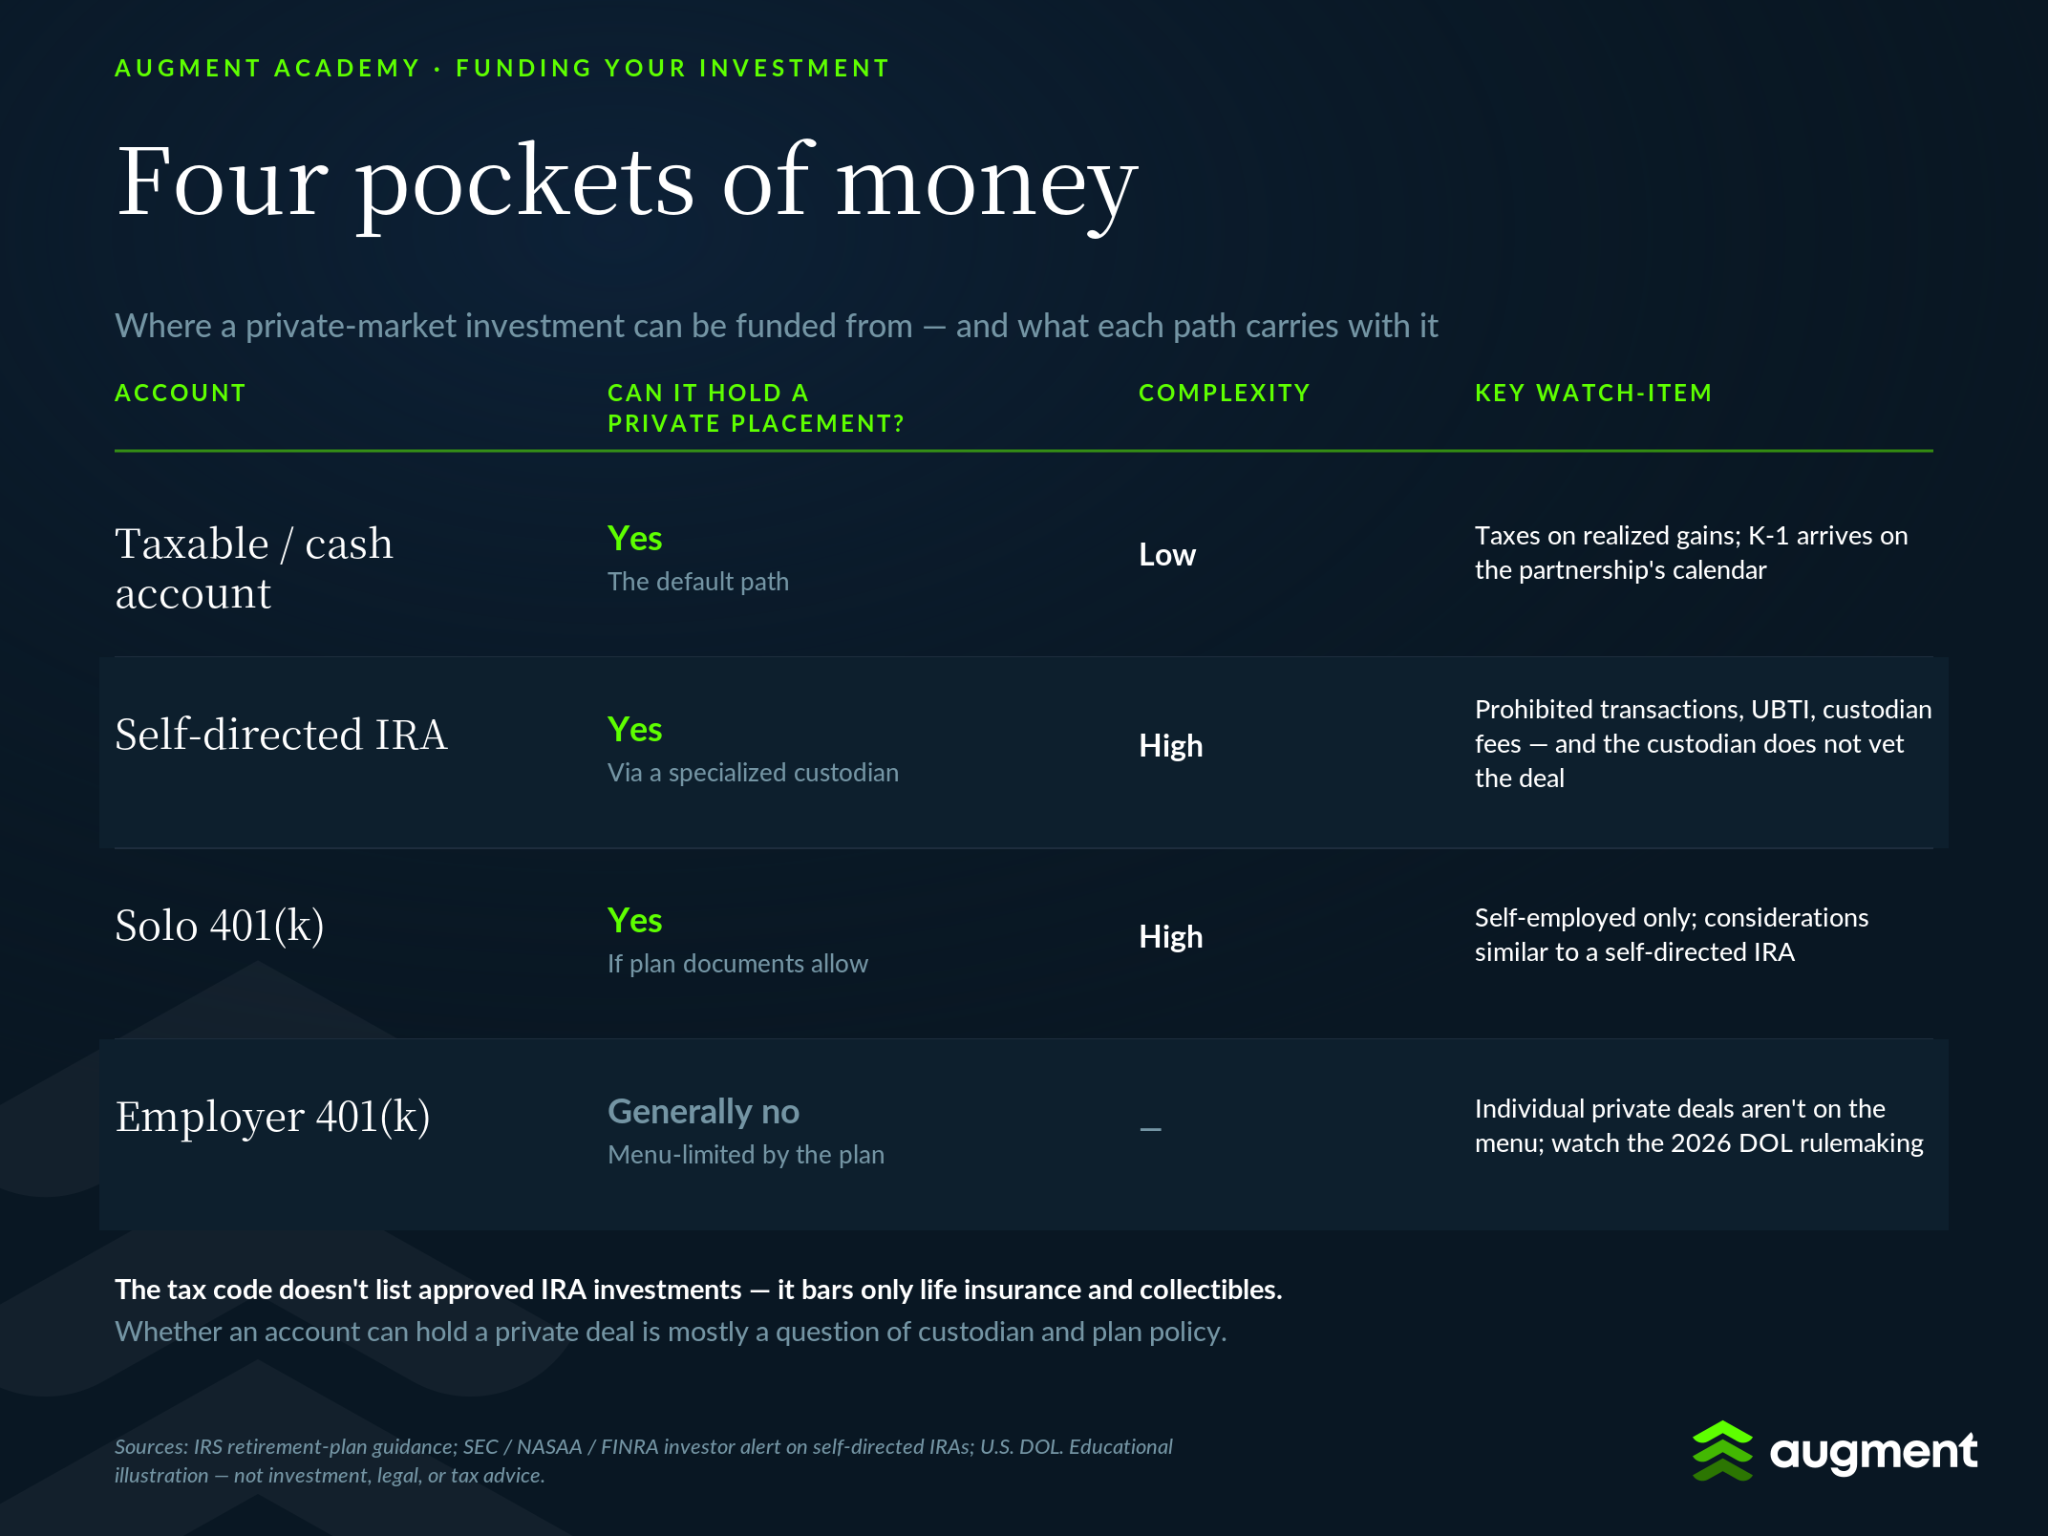
Four account types cover nearly every individual investor:
A solo 401(k) (a plan for self-employed people with no employees) can also hold private investments if its plan documents allow, with considerations similar to a self-directed IRA.
The tax code itself does not contain a list of approved IRA investments. IRS guidance identifies life insurance and collectibles as the investments IRA law specifically bars; private securities are not on that list. The reason your regular IRA can't buy into a private deal is that mainstream custodians often choose not to hold assets they can't price and settle automatically. A self-directed IRA is simply an IRA at a custodian that will.
Funding from a taxable account is straightforward: you subscribe, wire the money, and own the investment in your own name (typically as an interest in a special purpose vehicle (SPV), a fund entity formed to hold shares of a single company, covered in a separate module in this series, What You're Actually Buying in a Pre-IPO Deal). If you buy shares directly rather than through an SPV, there is no K-1: you hold the stock in your own name, and tax generally applies when you sell.
Most SPVs are limited liability companies taxed as partnerships and you'll generally receive a Schedule K-1 (a tax form reporting your share of the vehicle's income) each year, rather than the 1099 you get from a public brokerage account. Set your expectations on timing accordingly: partnerships must furnish K-1s by the partnership return's due date (March 15 for calendar-year partnerships, or September 15 with the automatic six-month extension), and private vehicles commonly take that extension, especially when they're waiting on tax information from underlying investments. In practice, a K-1 that arrives after the April personal-filing deadline is normal, and investors holding SPV interests often file a personal extension rather than plan around an early K-1. Taxes work the way they do for any investment held personally: no tax on unrealized appreciation, capital gains treatment when the investment is sold or distributed, though a K-1 can pass through taxable income in a given year even without a sale. Cost basis and holding periods are covered in the tax module of this series, How Are Pre-IPO Investments Taxed? Cost Basis, Holding Periods, and QSBS.
The taxable path is also the most flexible. There is no custodian intermediary, no distribution requirement, and no approval chain, which matters for investments that are illiquid and can stay that way for years.
Yes, through a self-directed IRA: an IRA held at a specialized custodian that permits a broader set of assets, including private placement securities. Investors typically fund one by rolling over part of an existing IRA or old 401(k). The custodian holds the investment in the account's name; capital goes out of the IRA, and any proceeds must come back into it.
The draw is the tax treatment: gains inside a traditional IRA are tax-deferred (and in a Roth, qualified distributions can be tax-free), and private investments' long holding periods sit naturally inside money you already can't touch until retirement.
But the SDIRA path carries four complications a taxable account doesn't:
The custodian is not vetting your deal. Regulators are direct about this: the SEC, FINRA, and state securities regulators have jointly warned that self-directed IRA custodians generally do not evaluate the quality or legitimacy of any investment; they hold and administer assets, nothing more. Fraud promoters sometimes claim otherwise. Diligence on the deal is entirely on you.
Prohibited-transaction rules. The tax code bars an IRA from transacting with "disqualified persons" (you, close family, and entities you control) under Section 4975 of the Internal Revenue Code. Buying shares from yourself, selling to your spouse, or personally benefiting from the IRA's investment can all cross the line. The penalty is severe: if an IRA owner engages in a prohibited transaction, the account stops being an IRA as of January 1 of that year and is treated as having distributed all its assets, potentially making the entire account taxable at once.
UBTI: the tax an IRA can still owe. An IRA is tax-exempt, but it still owes tax on unrelated business taxable income (UBTI). For a passive vehicle holding shares of a private company, ordinary investment income (dividends, interest, capital gains) is generally excluded from UBTI. The exposure arises mainly if the vehicle uses borrowed money (debt-financed income) or passes through income from an active business. If an IRA's gross UBTI reaches $1,000 in a year, the account must file Form 990-T and pay tax from the IRA's own assets. An unleveraged vehicle that simply holds shares doesn't generate UBTI, but exceptions exist. Ask the sponsor and your tax professional before subscribing.
Liquidity mismatch. Traditional IRAs eventually face required minimum distributions (RMDs), mandatory annual withdrawals once the owner reaches the applicable age. A private investment cannot be sold on demand to raise that cash. An investor whose IRA is heavily allocated to illiquid assets may find RMD funding awkward, which is why it matters to keep enough liquid assets in the account to cover foreseeable distributions.
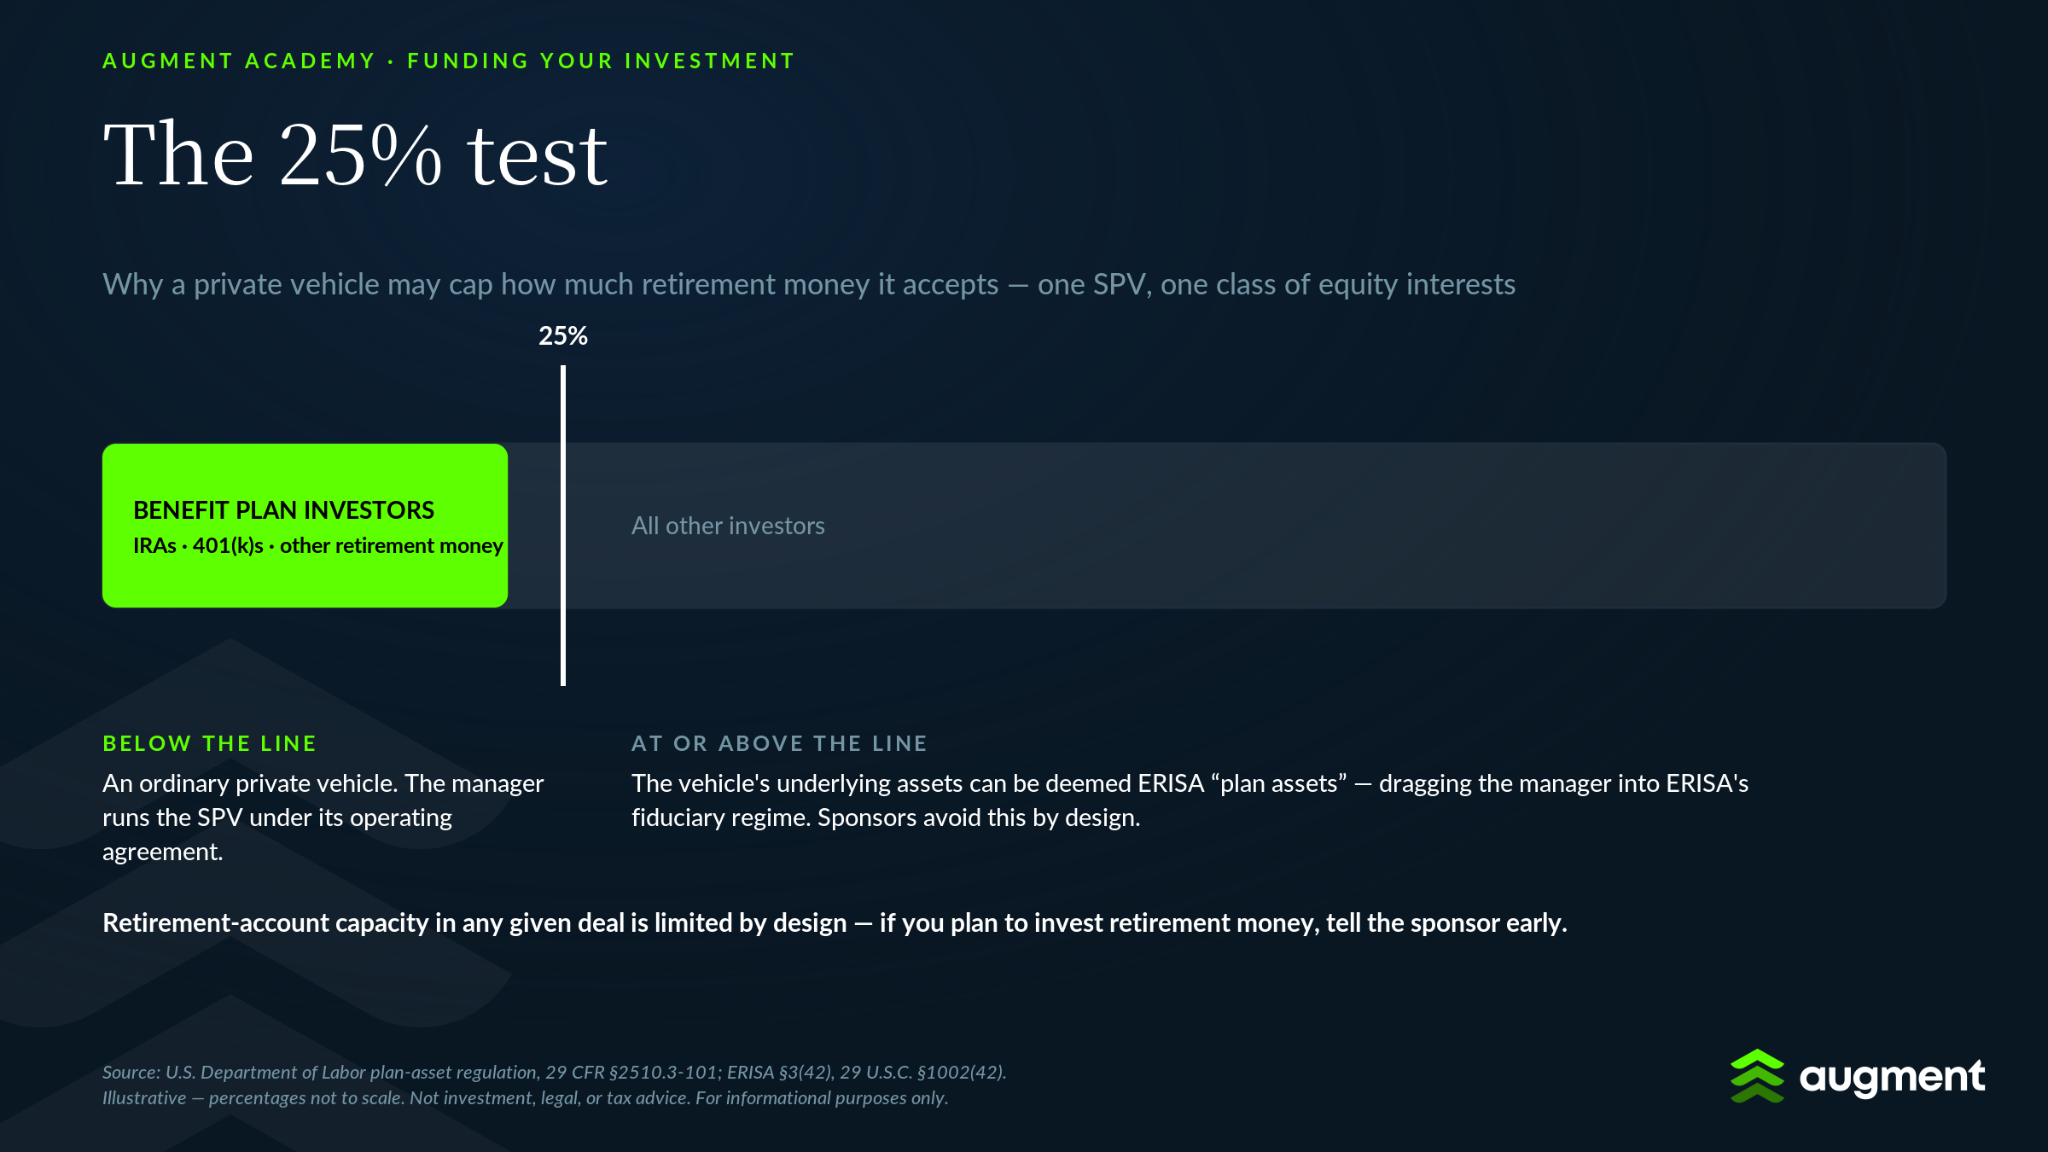
Even with a self-directed IRA fully set up, the vehicle itself may cap how much retirement money it can accept, and many investors first learn this at subscription.
Under the Department of Labor's plan-asset regulation, if 25% or more of any class of a private vehicle's equity interests is held by "benefit plan investors," the vehicle's underlying assets can be deemed "plan assets," which would drag the vehicle's manager into ERISA's fiduciary regime (the federal law governing retirement plans). Benefit plan investors include IRAs as well as employer plans.
Fund managers routinely avoid this by design, limiting benefit-plan-investor participation to under 25% of each equity class. So in any given deal, retirement-account capacity is limited. An SPV may accept your IRA subscription in full, scale it back, or decline it; that outcome often reflects the vehicle's 25% headroom across all its investors rather than anything about you. If you plan to invest retirement money, tell the sponsor early.
For individual pre-IPO deals, an employer 401(k) is generally not a path: participants invest from a menu of funds selected by the plan's fiduciaries, and individual private placements are not on it.
That is changing, though slowly. An August 2025 executive order directed regulators to expand access to alternative assets in defined-contribution plans, and in March 2026 the Department of Labor proposed a rule giving plan fiduciaries a process-based safe harbor for including alternative assets on plan menus. Two things to know about it: as of mid-2026 it remains a proposal, and it envisions alternatives inside professionally managed, diversified funds. Your 401(k) would gain exposure to private assets through a fund on the plan menu; picking a single-company private deal inside a 401(k) is not contemplated.
The taxable account is the simple, flexible default, with a K-1 and capital gains treatment. A self-directed IRA can work well for long-hold illiquid assets and brings tax deferral, at the cost of custodian fees, prohibited-transaction rules that carry account-ending penalties, a possible UBTI tax bill, and RMD planning. And in either retirement path, the deal itself may limit how much plan money it can take. Decide which pocket funds the investment before you subscribe. If it's retirement money, tell the sponsor early, and put the tax questions to a professional who can see your full situation.
Generally yes, through a self-directed IRA at a specialized custodian that handles private placements. Most mainstream IRA custodians choose not to offer them. Expect additional fees, prohibited-transaction rules, and possible UBTI filing obligations.
No. Offerings limited to accredited investors stay limited to accredited investors; for an IRA, eligibility generally looks to the account owner.
Unrelated business taxable income: income a tax-exempt account earns from an active business or debt-financed investments, on which the account owes tax despite its exempt status. Passive investment income (dividends, interest, capital gains) is generally excluded, so unleveraged single-company vehicles usually don't generate it. If gross UBTI reaches $1,000 in a year, the IRA files Form 990-T and pays tax from account assets.
Often the 25% test: private vehicles commonly keep benefit-plan-investor ownership (including IRAs) under 25% of each equity class so their assets aren't deemed ERISA "plan assets." Retirement-account capacity in any given deal is limited by design.
Employer plans generally don't offer individual private deals; participants choose from a fund menu. A March 2026 Department of Labor proposal would make it easier for plan menus to include diversified funds with alternative-asset exposure, but it was not final as of mid-2026 and would not enable picking single-company deals inside a 401(k). Self-employed investors with a solo 401(k) have more latitude, similar to a self-directed IRA.
Get started today — explore pricing, offerings, and submit your first order.
FOR QUALIFIED INSTITUTIONAL AND ACCREDITED INVESTORS ONLY: Under federal securities laws, private market investments on this platform are available exclusively to Institutional and Accredited Investors. Verification of status required before investing. Private investments involve significant risks including illiquidity, potential loss of principal, and limited disclosure requirements. "Augment" refers to Augment Markets, Inc. and its affiliates. Augment Markets, Inc. is a technology company offering software and data services, not a bank or financial institution. Cash Accounts are provided by Modern Treasury Corp. financial institution partners and through Augment's technology. Augment does not act as a money services business, provide money transmission, or serve as a custodian of funds. Funds held in your Cash Account are not FDIC insured unless expressly disclosed. Full terms available in the Augment Cash Account Agreement.Brokerage services are offered through Augment Capital, LLC, an affiliated broker-dealer and member FINRA/SIPC. “Investment accounts” are not brokerage accounts and do not hold customer funds or securities. Investment advisory services are offered through Augment Advisors, LLC, an SEC-registered investment adviser. Registration with the SEC does not imply a certain level of skill or training. Augment and its affiliates do not provide legal or tax advice; consult your attorney or tax professional regarding your specific situation. For additional information, please refer to Augment Advisors, LLC’s Form ADV Part 2A (Firm Brochure) and FINRA BrokerCheck.